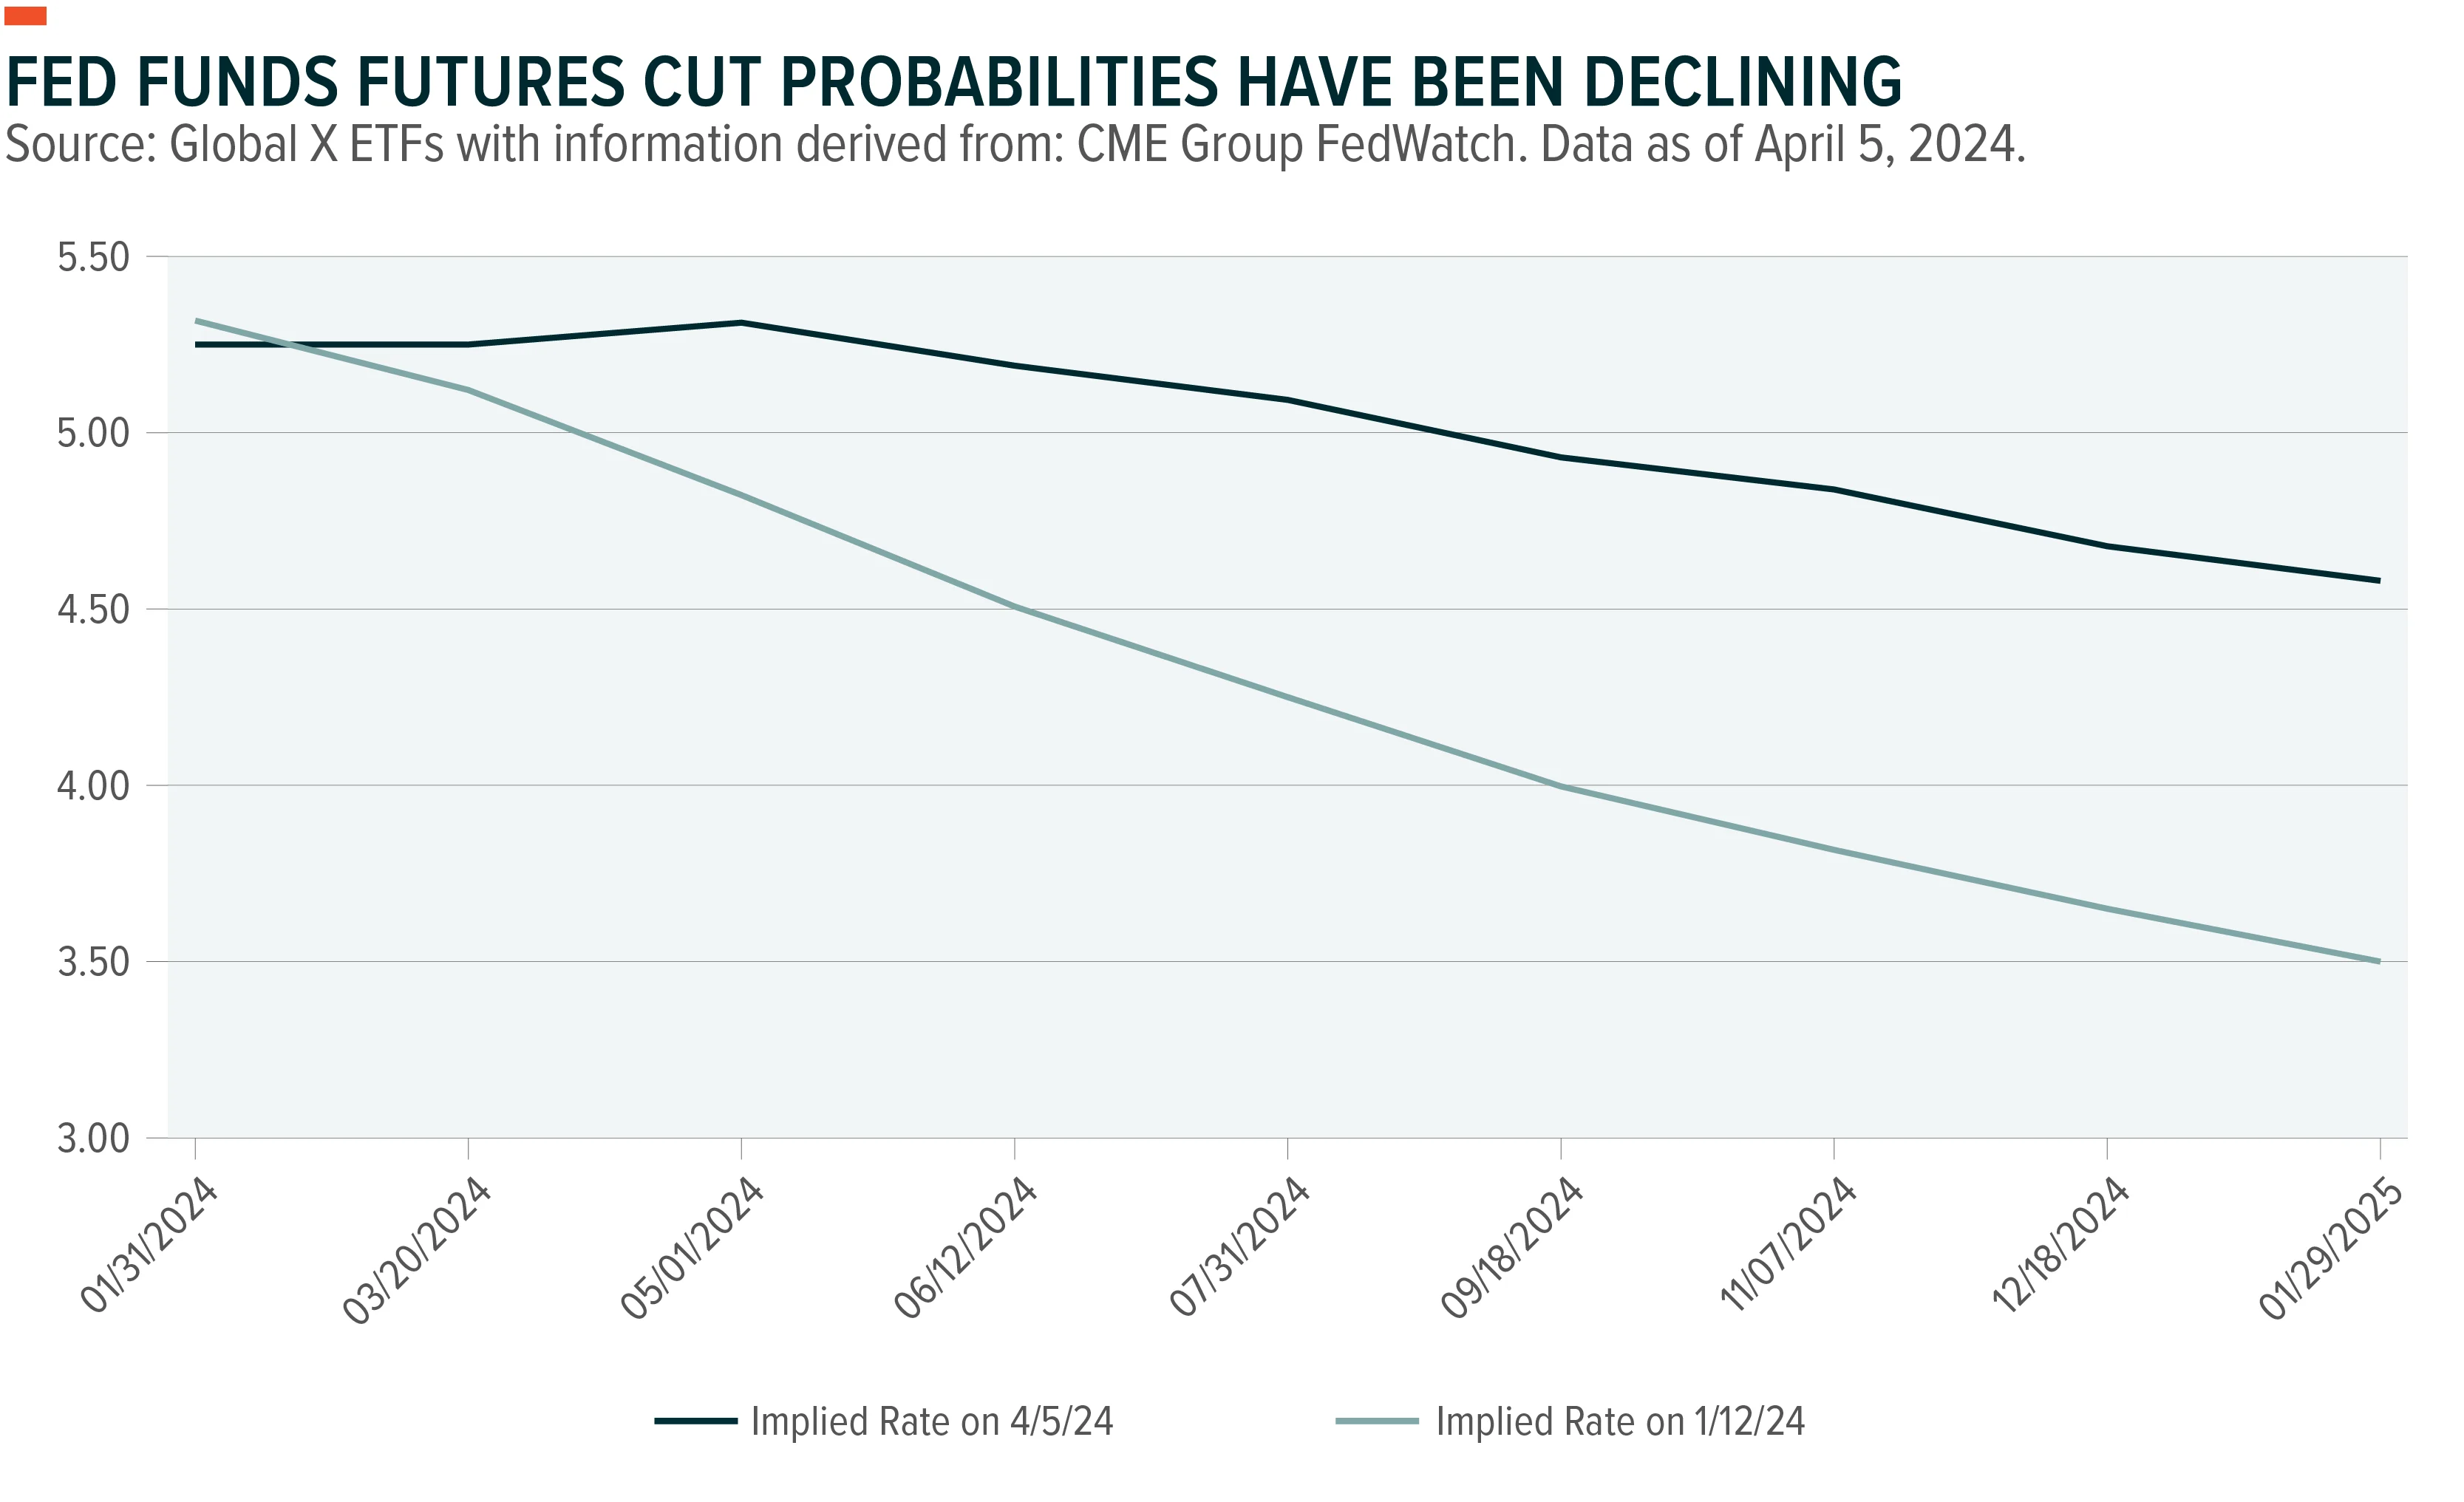
Heading into 2024, markets anticipated the Fed monetary policy easing cycle to kickstart performance. Investors questioned what type of landing we would have but saw the lower cost of capital not only spurring economic growth but also driving multiple expansion. However, since the beginning of the year, the market’s easing expectations have declined from seven cuts to just two.1 So the question is, if rate cut expectations have been pushed back, why are emerging market (EM) assets rallying?
Key Takeaways
Emerging market equities have shown strength even in the face of “higher for longer” interest rate expectations, and we think the momentum can continue.
Global economic growth is accelerating, and EMs could be outsized beneficiaries due to their exposure to commodities, manufacturing, and industrials.
The cyclical tailwind we see for EM equities will likely outweigh interest rate volatility, but interest rate cuts by the U.S. Fed could provide an additional catalyst for multiple expansion.
Nearing a Global Cyclical Bottom
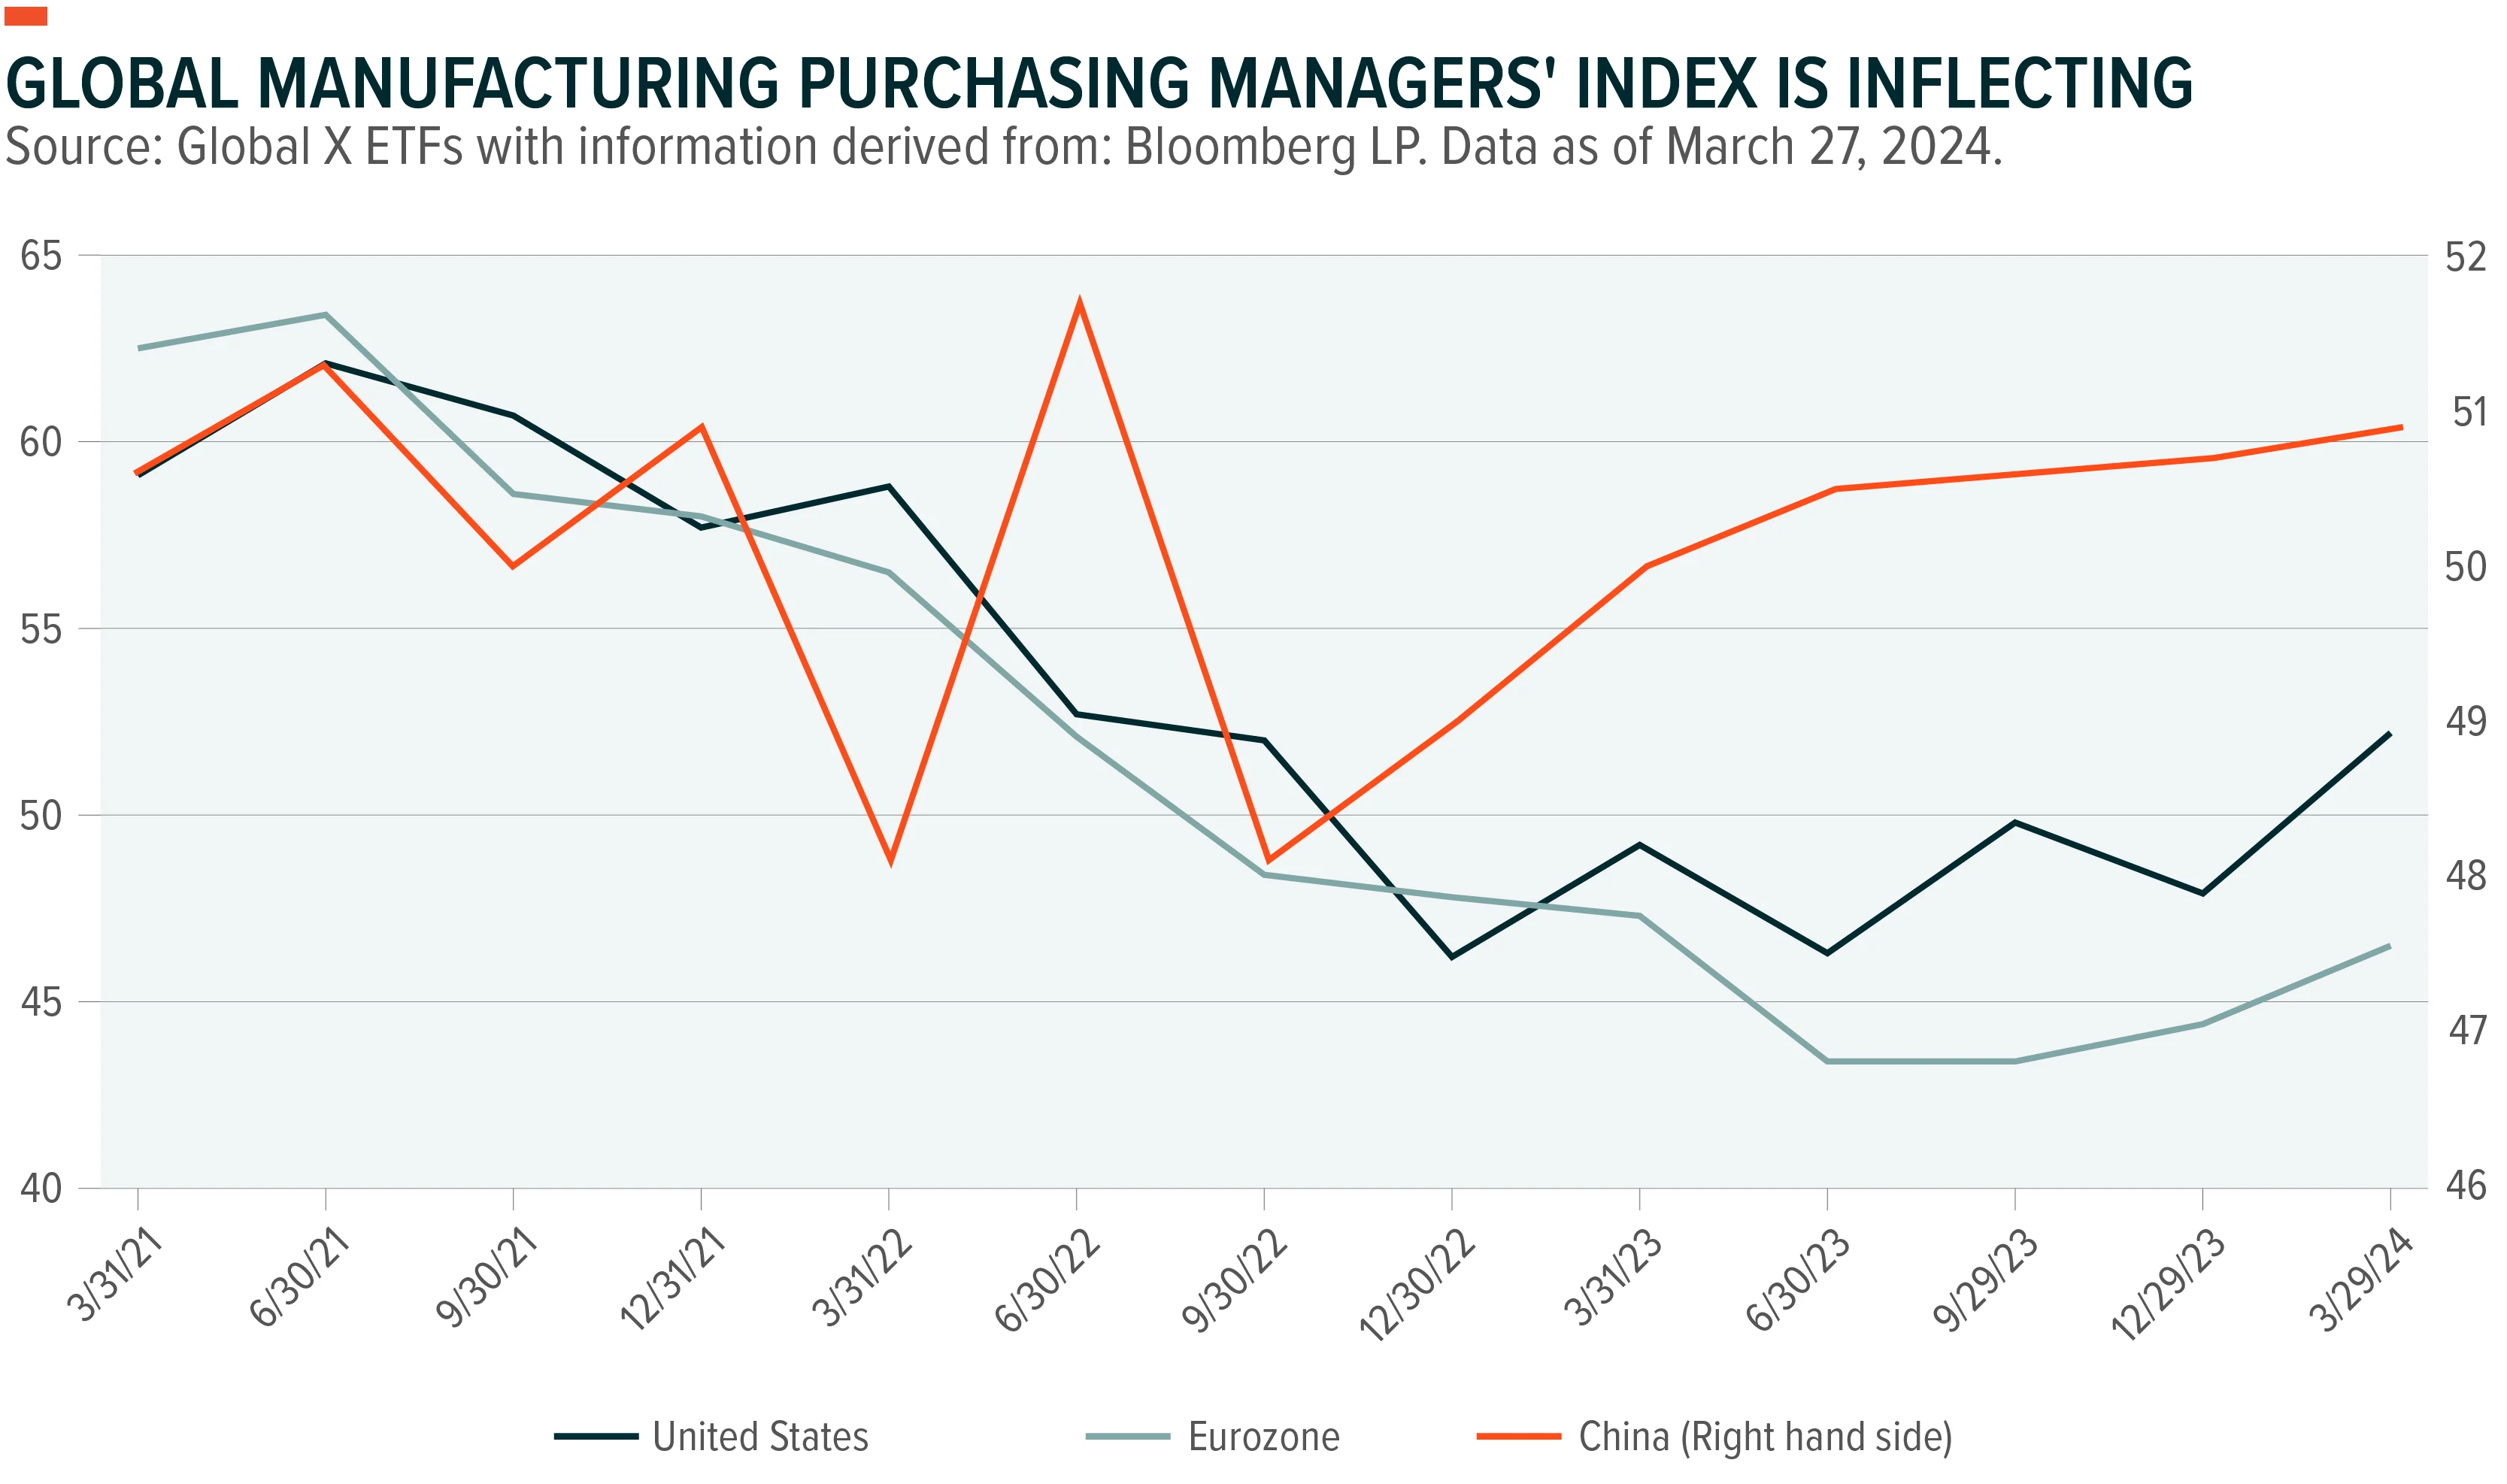
Following the initial post-pandemic reopening boom in global economic growth, we saw a sharp slowdown in goods consumption, putting outsized pressure on the global industrial and manufacturing sectors. This weighed significantly on exporting countries, such as China and Vietnam, as well as commodity-driven economies like Brazil and Chile. However, looking ahead, we see signs that the cycle is turning, with all major global purchasing managers’ indexes (PMIs) improving and the U.S. and China now in expansionary territory. We have also seen green shoots in certain commodities, with copper and Brent crude rising 18% and 24% respectively off their recent lows.2 A rally in the face of a “higher for longer” shift is remarkable and suggests performance has been driven more by supply and demand dynamics than interest rate predictions. Data and markets continue to signal that we have reached a cyclical bottom, potentially providing a powerful backdrop for the global growth outlook.
What if the Fed Doesn’t Cut?
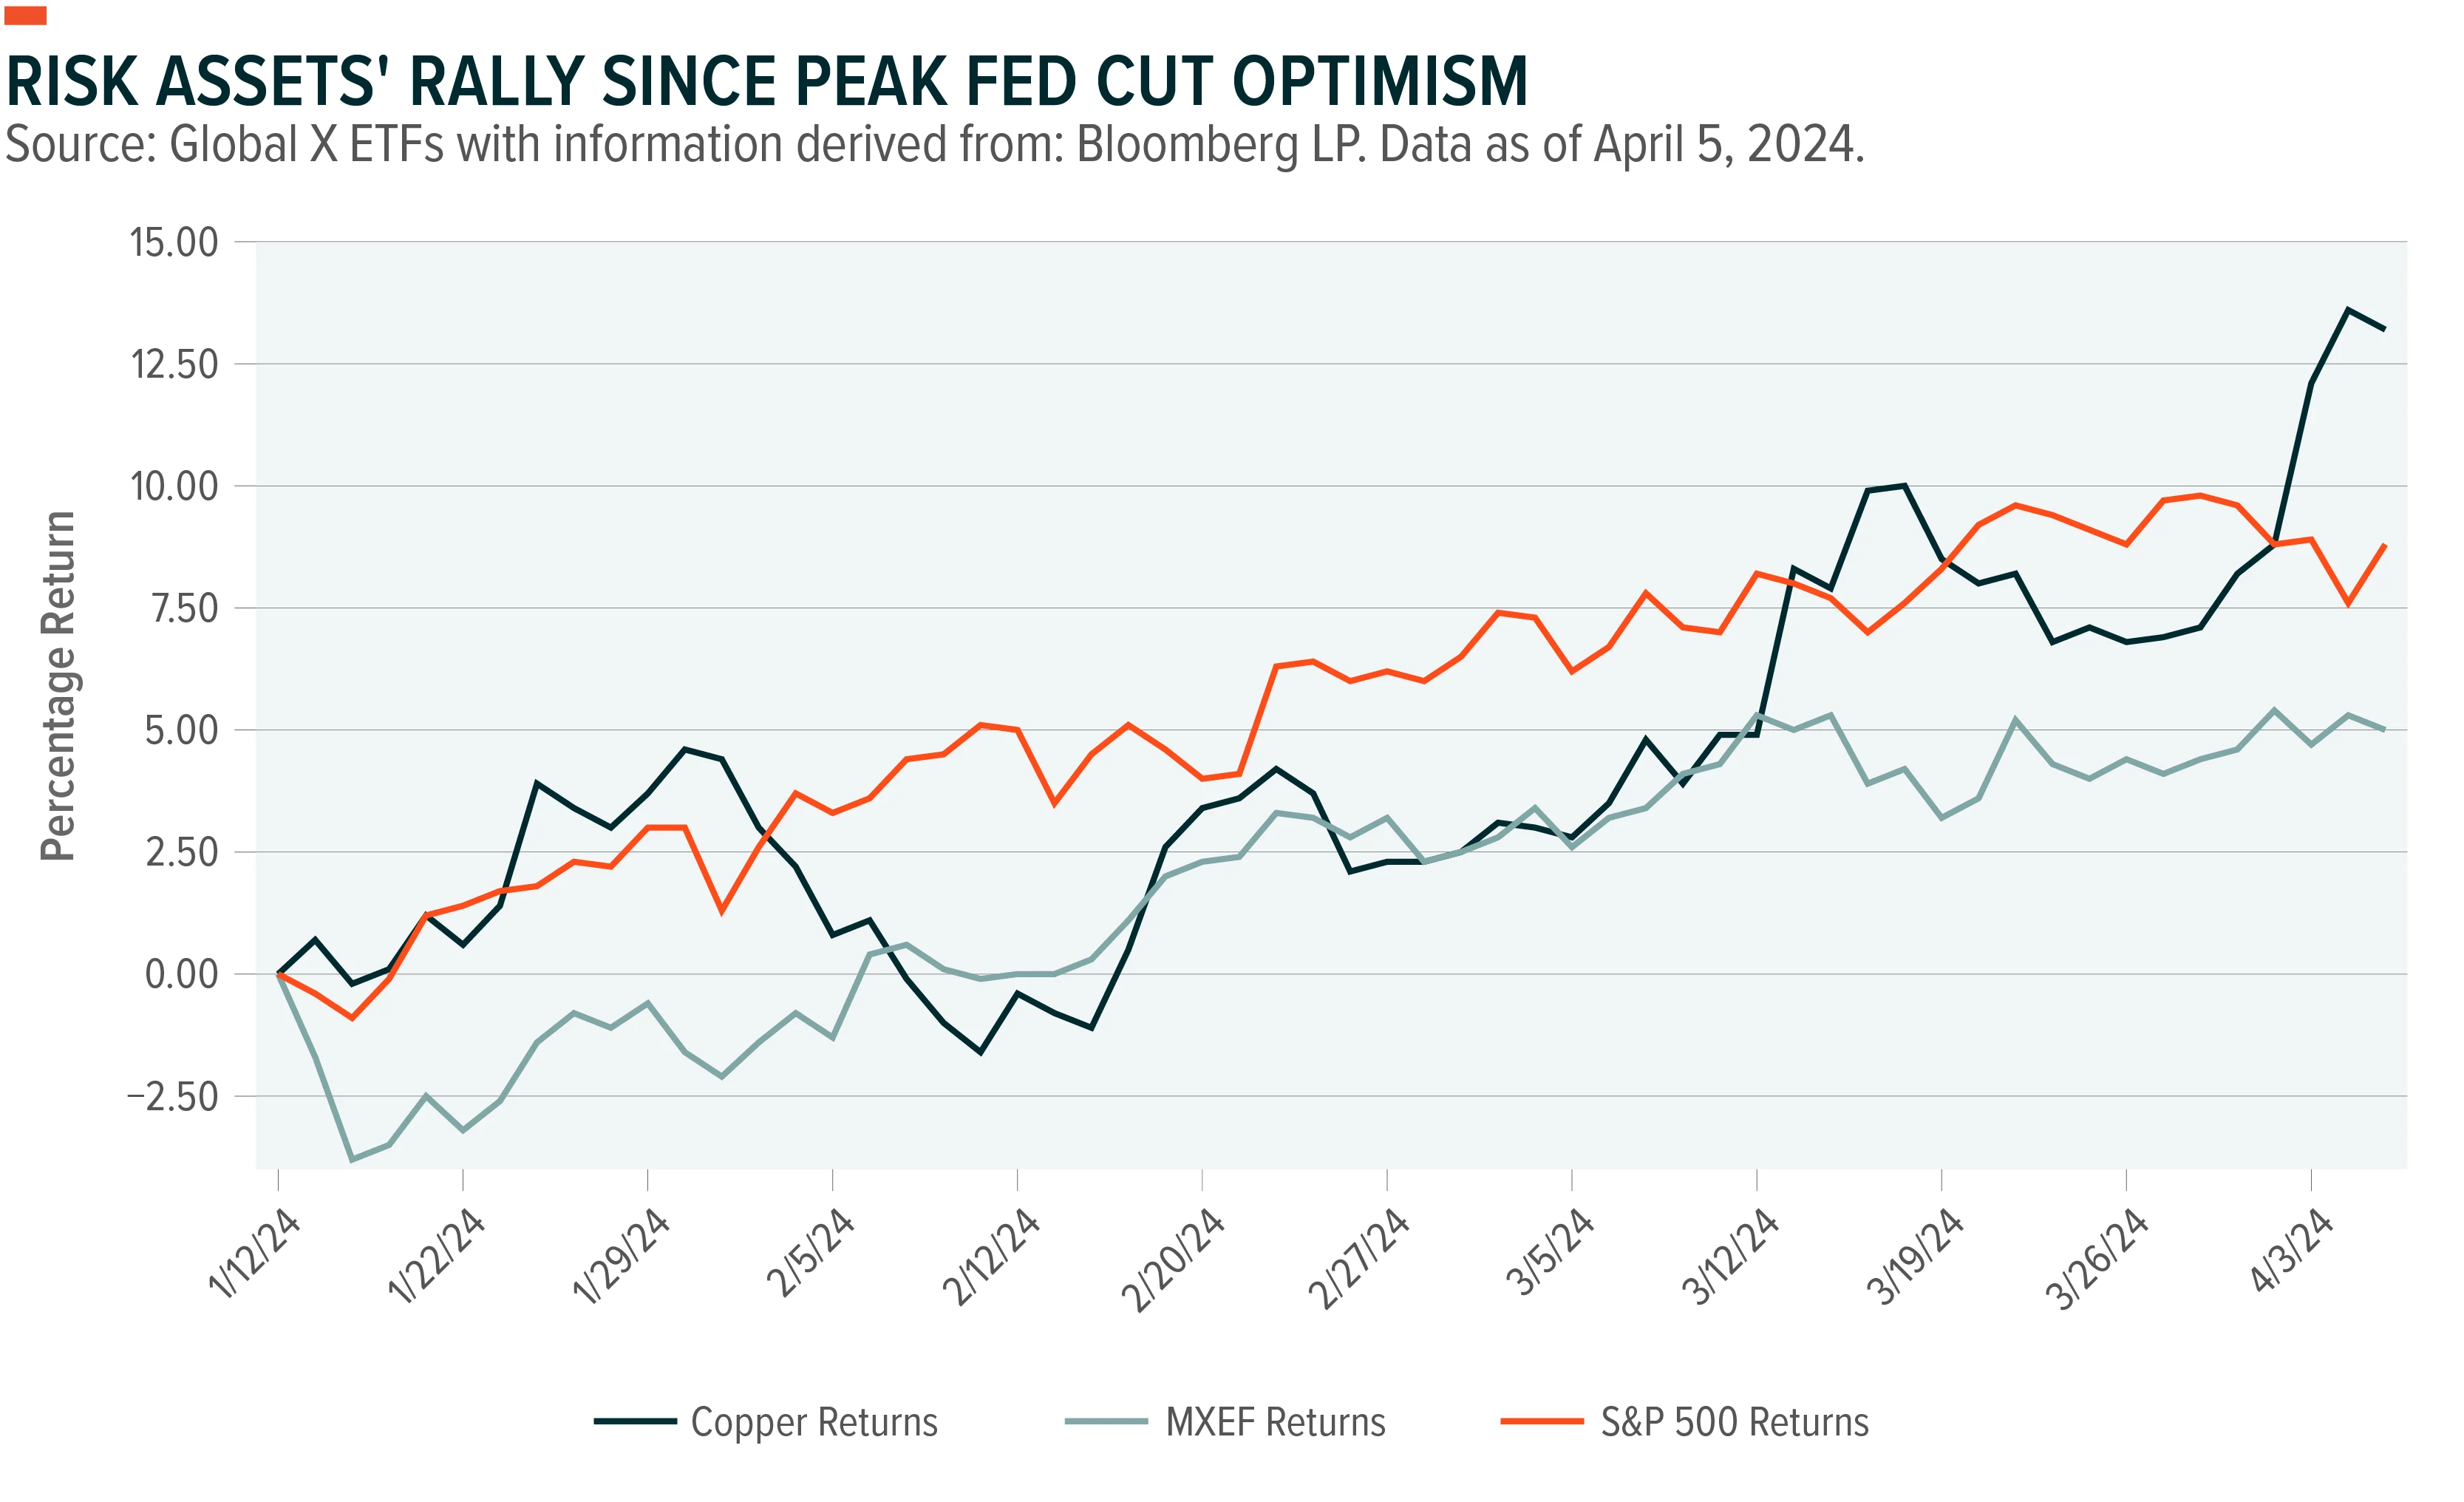
Risk assets have posted strong year-to-date performances, despite the market pricing in a more hawkish Fed. We believe this is because of the cyclical tailwind discussed above, and we see the gold market as particularly telling. The bullion has rallied to multiple all-time highs thus far in 2024, despite the higher Fed Funds Rate expectation, making us believe the market is pricing in reflation, and subsequently lower real interest rates, resulting from the anticipated economic acceleration. Looking ahead, we continue to believe this cyclical tailwind will outweigh interest rate volatility. We also note that the 50 basis points (bps) of cuts currently priced into markets for 2024 is smaller than the retracement seen so far YTD and well below the over 500bps of hikes seen in the 2022/23 hiking cycle. So even in a situation where the FOMC doesn’t cut rates, which is not our or the market’s base case, we remain positive on EM assets.
Why Emerging Market Equities Stand Out in This Context
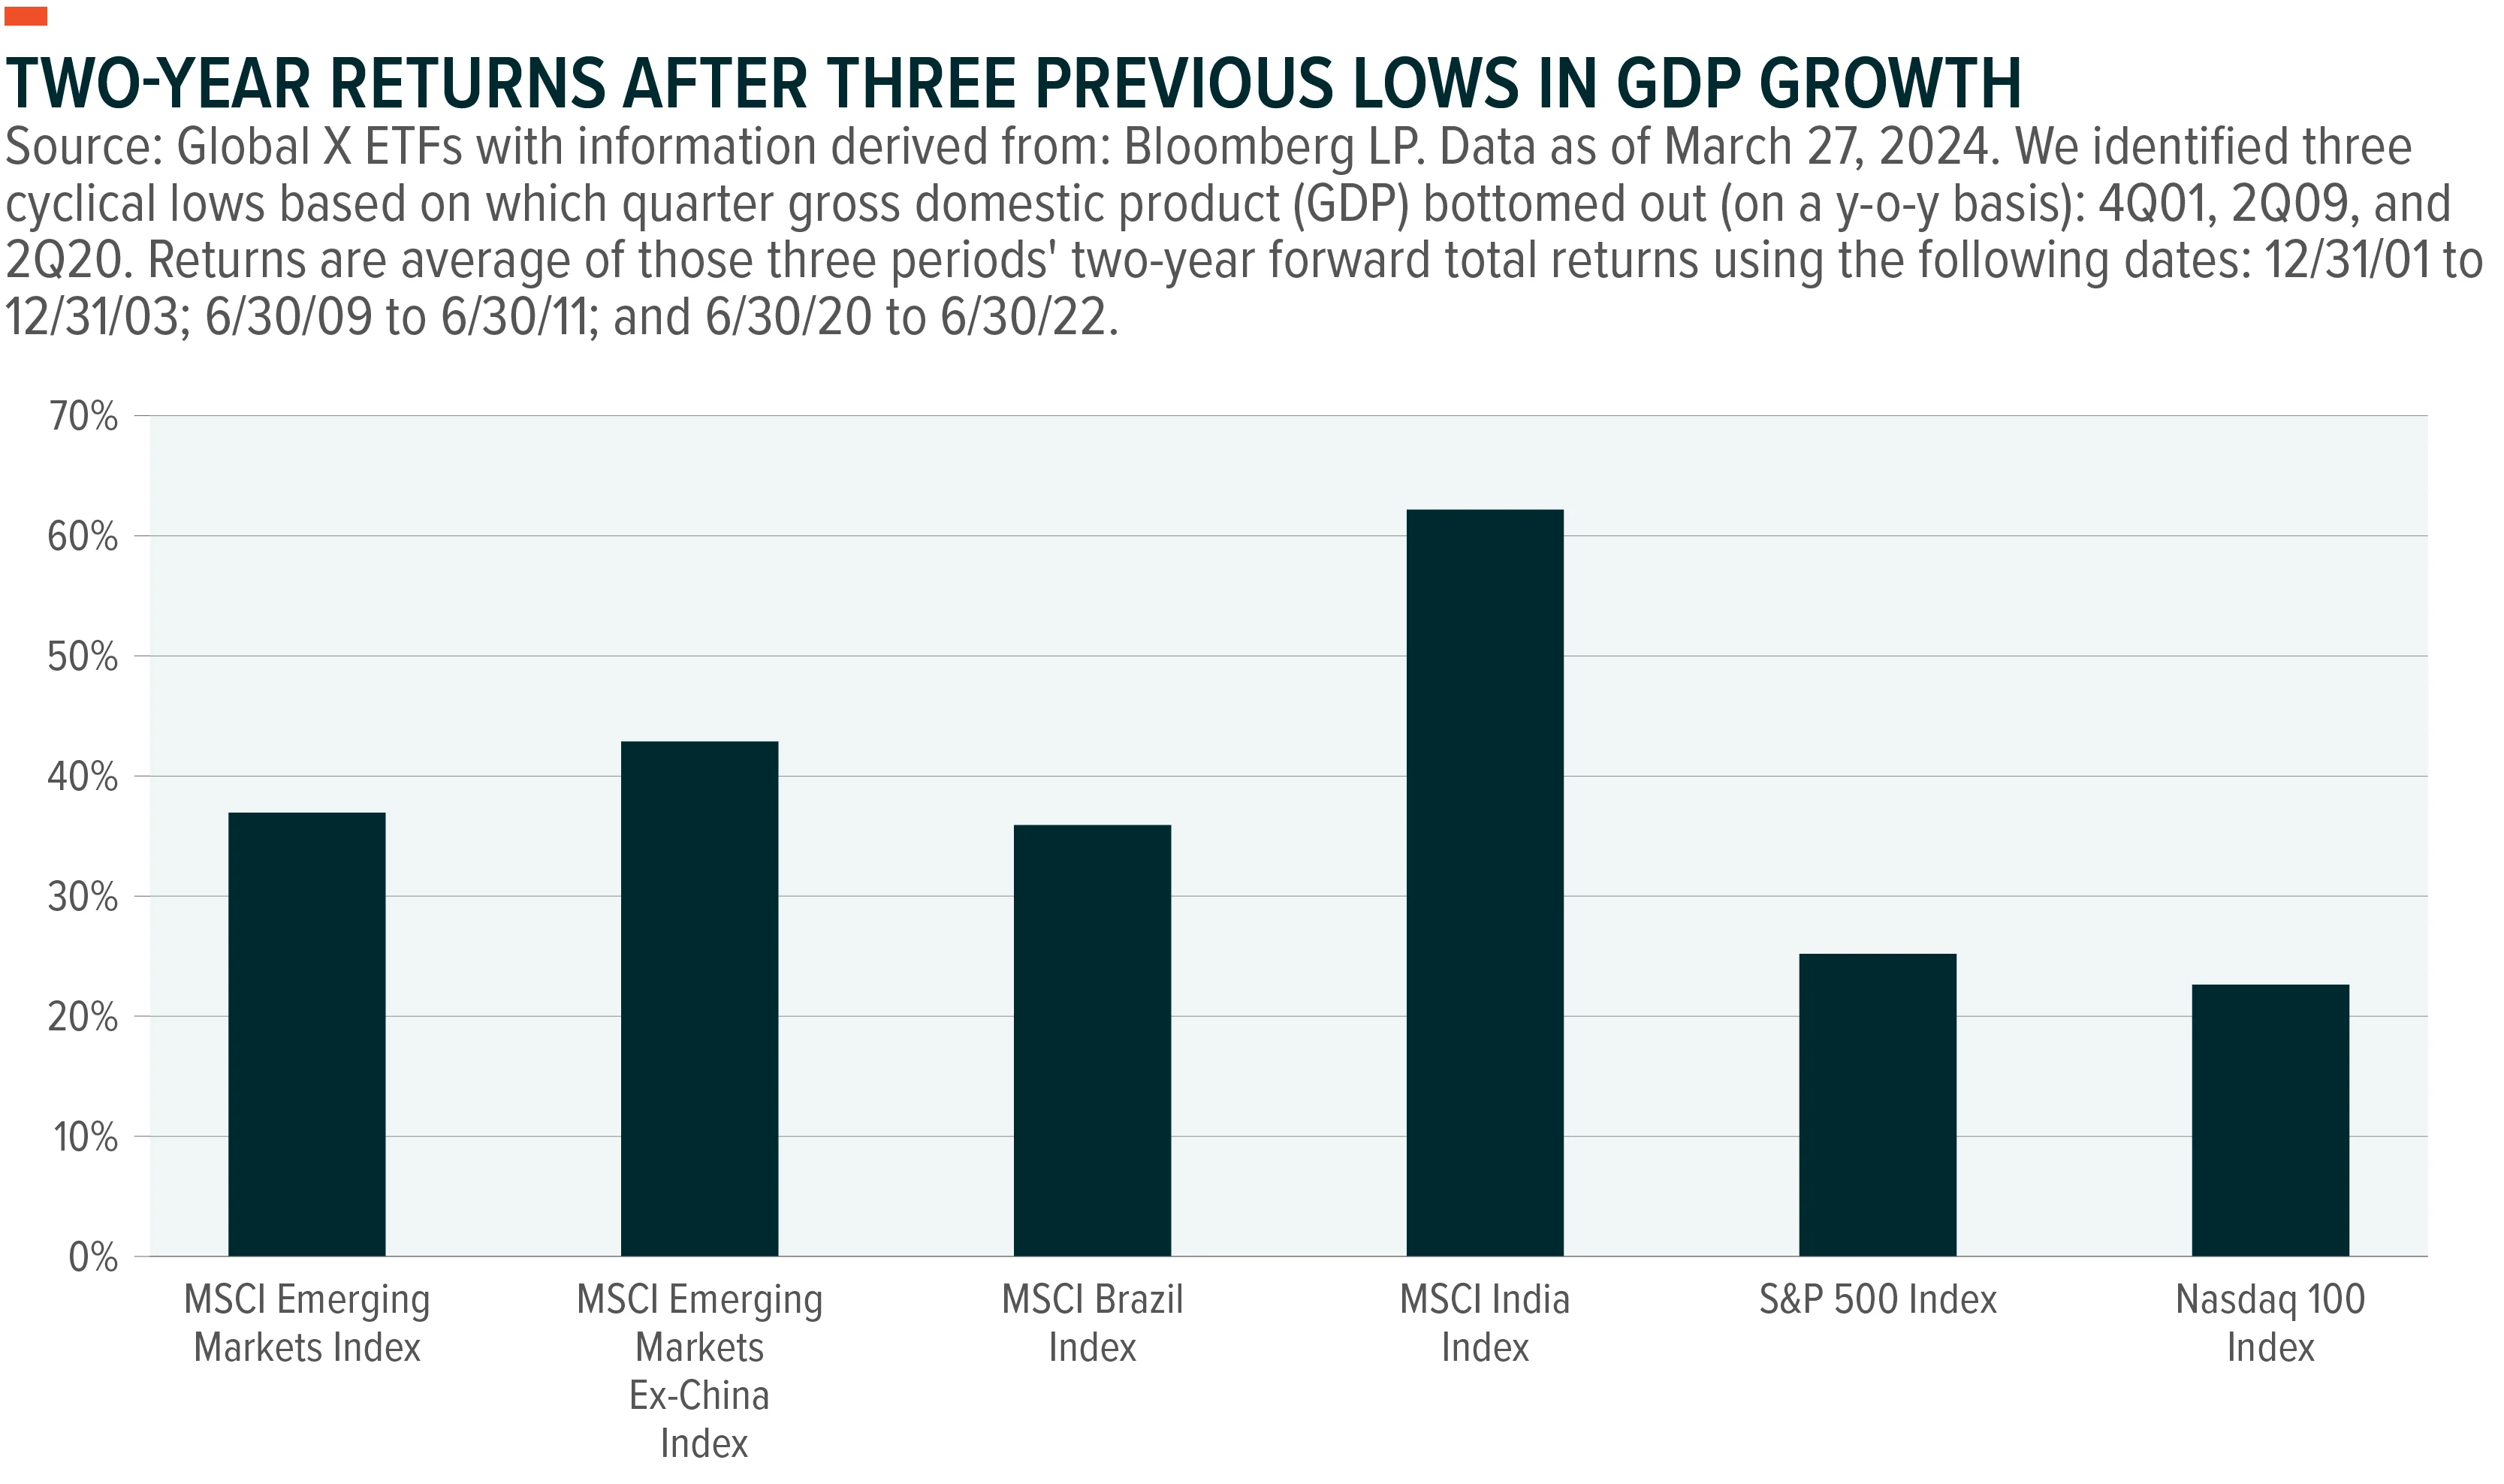
We believe EM equities stand to be outsized beneficiaries of this global economic growth acceleration for three main reasons.
Conclusion
We believe that global economic growth bottomed and now is poised to reaccelerate throughout the remainder of 2024. The cyclical nature of EM economies likely positions them well to be outsized beneficiaries of this trend. The recent rally in the face of declining Fed rate cut expectations is encouraging, with the two expected cuts potentially set to be an additional catalyst for EM equity multiple expansion. Overall, this powerful cyclical tailwind makes us more positive on our bullish view for EM equities, an asset class that we feel is overlooked, underpriced, and now ripe for outperformance.