Skip to Main Content
Subscribe to Newsletters
Global X Logo
Search
Content loaded

Explore

Our ETFs

Investment Insights

Thought LeadershipProduct ResearchCharting DisruptionMidyear Outlook 2026

Investor Resources

EducationHow to InvestTax Resources

About Us

About Global XNewsroomCareersContact Us

Follow Us

socaial media icon for LinkedInLinkedInSocial media icon for X (twitter)XSocial media icon for FacebookFacebookSocial media icon for InstagramInstagramSocial media icon for Youtube

Copyright © 2026 Global X. All rights reserved.

Privacy PolicyAccessibility Statement
YouTube

Subscribe to our newsletter

Get the latest news and updates from our team.

Subscribe

SEI Investments Distribution Co. (1 Freedom Valley Drive, Oaks, PA, 19456) is the distributor for the Global X Funds.

Check the background of SIDCO and Global X's Registered Representatives on FINRA's BrokerCheck.

Content
Product ResearchInternationalActive Emerging

Global X Brazil Active ETF (BRAZ) 3Q26 Commentary

x
M
Multiple authors
Oct 28, 2026·3 min read

Brazilian equities rose in the third quarter as higher oil prices lifted energy, the central bank kept cutting rates and foreign flows returned in September. BRAZ outperformed its benchmark, led by its Materials holdings

Market Review

Brazilian equities rose 8.18% in the third quarter, led by energy.1 Brent crude rose more than 20% in July after a pause in the US-Iran conflict collapsed,2 and MSCI Brazil Index (“the benchmark”) Energy stocks returned 31.50%.3 The Central Bank of Brazil cut the benchmark interest rate, Selic, by 25 basis points in both August and September, to 13.75%, as twelve-month inflation eased to 4.22%.4 The real ended the quarter little changed against the dollar,5 even as the Federal Reserve raised rates in September.6 Foreign investors withdrew R$18.1 bln from B3, Brazil’s main stock exchange, in August, then returned R$9.6 bln in September through the 28th.7 Dispersion ran wide within the benchmark. Consumer Discretionary, led by Ultrapar, rose 34.25%, while Communication Services fell 12.76%, Materials 2.85% and Consumer Staples 2.54%.8

Fund Performance & Attribution

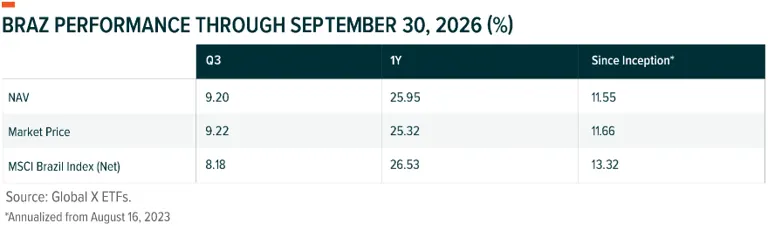
BRAZ outperformed the MSCI Brazil Index for the quarter by 102 basis points. Year to date, BRAZ returned 17.15% at NAV versus 18.24% for the benchmark.9 This attribution nets each issuer’s local and ADR lines into one position, isolating the stock decision from the vehicle.10

  • Contributors: From a sector perspective, Materials, Consumer Staples and Utilities added the most. Stock selection drove each: BRAZ held underweights of 0.66, 1.08 and 1.69 percentage points, but its holdings returned 7.53%, 4.22% and 3.26% against -2.85%, -2.54% and 0.98% for the benchmark sectors. In terms of individual securities, overweights in Ero Copper (2.64%, not in the benchmark), BTG Pactual (4.86% versus 2.70%) and Aura Minerals (1.55% versus 0.50%) contributed most. A net underweight in Vale (6.80% versus 10.76%) also helped as the stock fell.

  • Detractors: From a sector perspective, Consumer Discretionary, Industrials and Health Care lagged. BRAZ held a 2.90 percentage point overweight in Consumer Discretionary, where its holdings returned -2.85% against 34.25% for the benchmark sector. In terms of individual securities, Direcional Engenharia, which the benchmark does not hold, the absence of Ultrapar, which rose 48.85%, and XP Inc detracted most. BRAZ added XP late in the quarter, so it carried an average weight of 0.29% against 1.45% for the benchmark as the stock rose 29.12%.

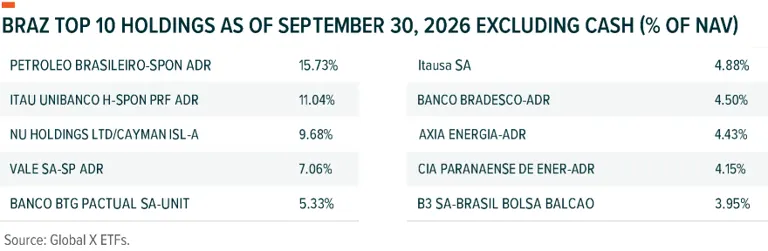
This quarter we added XP Inc and sold Suzano and BR Advisory Partners.11
Global X Brazil Active ETF (BRAZ) 3Q26 Commentary image 1

The performance data quoted represents past performance. Past performance does not guarantee future results. The investment return and principal value of an investment will fluctuate so that an investor's shares, when sold or redeemed, may be worth more or less than their original cost and current performance may be lower or higher than the performance quoted. High short-term performance, when observed, is unusual and investors should not expect such performance to be repeated. Performance current to the most recent quarter- and month-end is available at https://www.globalxetfs.com/funds/braz/. Expense Ratio: 0.75%.
Global X Brazil Active ETF (BRAZ) 3Q26 Commentary image2

Holdings are subject to change.

Outlook

We stay constructive on Brazil heading into the fourth quarter based on 4 factors:

Risks include the October 25 presidential runoff and the fiscal path that follows,15 volatile oil prices, further Federal Reserve tightening and renewed foreign outflows.

Why This Fund

Despite mid-to-high teen returns on equity and solid growth prospects, the MSCI Brazil Index trades at a high single digit price-to-earnings ratio and offers a dividend yield above 6%.16 We believe active management helps investors navigate dispersion across Brazilian sectors and stocks, as the third quarter showed. BRAZ applies bottom-up fundamental analysis to find quality businesses with strong management teams and domestic-driven growth over a four to five year horizon, with the fees, liquidity, transparency, and potential tax efficiency of its ETF structure.17

Related ETF

BRAZ – Global X Brazil Active ETF

Click the fund name above to view current performance and holdings. Holdings are subject to change. Current and future holdings are subject to risk.

Valuation: After the early-October rally, Brazil trades at 9.3 times two-year-forward earnings, roughly 50% below the 18.5 times for the S&P 500.12

Income: Brazil’s two-year-forward dividend yield of 6.33% compares with 1.17% for the S&P 500.13

Monetary easing: The Selic stands at 13.75% after five consecutive cuts, and the Focus survey projects more cuts, which could support domestic-facing earnings.14

Politics: Brazil is hosting the second round of its presidential election on October 25th

Related articles

1of3
Thought LeadershipBrazilEmerging Markets

Why Brazil? Why BRAZ?

We believe Brazil’s current backdrop of attractive valuations, monetary easing, and upcoming elections creates a timely opportunity for active investing.

M

Multiple authors

Sep 1, 20261 min read
Thought LeadershipEmerging MarketsChina

Why EM Ex-China? Why EMM?

Product ResearchArgentinaSouth America

Post-Primaries: Q3 Argentina Update

Thought LeadershipBrazilEmerging Markets

Why Brazil? Why BRAZ?

We believe Brazil’s current backdrop of attractive valuations, monetary easing, and upcoming elections creates a timely opportunity for active investing.

Related funds
International
BRAZBrazil Active ETF
Explore All ETFs
Footnotes

1. Global X ETFs. BRAZ Performance History, cumulative returns as of September 30, 2026 (benchmark: MSCI Brazil Index net return of 8.18% for the quarter and 18.24% year to date).

2. Rigzone (Bloomberg wire). "Brent Caps Strongest Month Since March." Published July 31, 2026 (Brent up nearly 24% in July); U.S. Energy Information Administration. "Crude oil prices and refinery margins generally increased throughout the third quarter." Today in Energy, October 5, 2026 (front-month Brent near $72 on July 1; above $100 on July 23).

3. Bloomberg LP. PORT attribution, BRAZ versus MSCI Brazil Index (NDUEBRAF Index), quarter ended September 30, 2026, benchmark sector returns.

4. Rádio Itatiaia. "Banco Central realiza quinto corte seguido na taxa Selic." Published September 16, 2026 (Selic cut to 13.75% from 14.00%); B+L Marktdaten. "Brazil’s Central Bank Cuts Selic to 14%, Fourth Straight Reduction." Published August 7, 2026 (cut of August 5, 2026); Diário do Grande ABC. "IPCA em 12 meses fica em 4,22% e segue dentro da meta em agosto." Published September 11, 2026 (IBGE data).

5. Agência Brasil. "Dólar cai para R$ 5,17 e acumula recuo de 0,15% em setembro." Published September 30, 2026 (dollar up 0.23% against the real in the third quarter).

6. Board of Governors of the Federal Reserve System. "Federal Reserve Issues FOMC Statement." Press release, September 16, 2026; Trading Economics. "Fed Raises Rates for 1st Time Since 2023." Published September 16, 2026.

7. Agências. "Ibovespa sobe 5% no mês e 8% no 3º trimestre, com fluxo estrangeiro e trade eleitoral." Jornal do Comércio. Published September 30, 2026 (B3 data on foreign investor flows).

8. Bloomberg LP. PORT attribution, BRAZ versus MSCI Brazil Index (NDUEBRAF Index), quarter ended September 30, 2026, benchmark sector returns.

9. Global X ETFs. BRAZ Performance History, cumulative returns as of September 30, 2026 (fund NAV and benchmark returns).

10. Bloomberg LP. PORT attribution, BRAZ versus MSCI Brazil Index (NDUEBRAF Index), quarter ended September 30, 2026. Local and ADR lines of the same issuer are combined. Overweights and underweights compare average portfolio weights with average benchmark weights over the quarter.

11. Bloomberg LP. BRAZ holdings as of June 30, 2026 and September 30, 2026. Adds and sells reflect positions absent at one date and present at the other.

12. Bloomberg LP. MSCI Brazil Index (MXBR Index) and S&P 500 Index (SPX Index), price-to-earnings ratio on two-year estimates (2GY Est), as of October 7, 2026 (MXBR 9.28x; SPX 18.52x). The reading includes market moves after September 30, 2026.

13. Ibid. Dividend yield on two-year estimates: MXBR 6.33%; SPX 1.17%.

14. Diário do Grande ABC. "Selic no fim de 2026 passa de 13,75% para 13,50%, aponta Focus." Published September 21, 2026 (Banco Central do Brasil Focus survey).

15. Jornal Opção. "Eleições: TSE aprova calendário eleitoral oficial de 2026." Published March 3, 2026 (first round October 4, 2026; runoff October 25, 2026, if no candidate wins an absolute majority).

16. Bloomberg LP. MSCI Brazil Index (MXBR Index), as of October 7, 2026: return on equity, price-to-earnings ratio on two-year estimates of 9.28x and dividend yield on two-year estimates of 6.33% (see notes 12 and 13).

17. Global X ETFs. Global X Brazil Active ETF (BRAZ), fund page, accessed October 8, 2026 (actively managed ETF seeking long-term capital growth through direct exposure to the Brazilian economy; screens for quality business models and management teams, with domestic-driven growth over a four to five year horizon). Tax efficiency is not guaranteed.

EM ex-China is attracting attention as investors look beyond China to opportunities in technology, demographics, and supply chain shifts.

M

Malcolm Dorson

Sep 3, 20260 min read

Here is our outlook for Argentina following surprising primary results that disrupted a record year.

G

Global X Research

Aug 26, 20195 min read
M

Multiple authors

Sep 1, 20261 min read
Thought LeadershipEmerging MarketsChina

Why EM Ex-China? Why EMM?

EM ex-China is attracting attention as investors look beyond China to opportunities in technology, demographics, and supply chain shifts.

M

Malcolm Dorson

Sep 3, 20260 min read
Product ResearchArgentinaSouth America

Post-Primaries: Q3 Argentina Update

Here is our outlook for Argentina following surprising primary results that disrupted a record year.

G

Global X Research

Aug 26, 20195 min read