Skip to Main Content
Subscribe to Newsletters
Global X Logo
Search
Content loaded

Subscribe to our newsletter

Get the latest news and updates from our team.

Subscribe

Explore

Our ETFs

Investment Insights

Product ResearchCharting DisruptionMidyear Outlook 2026

Investor Resources

EducationHow to InvestTax Resources

About Us

About Global XNewsroomCareersContact Us

Follow Us

socaial media icon for LinkedInLinkedInSocial media icon for X (twitter)XSocial media icon for FacebookFacebookSocial media icon for InstagramInstagramSocial media icon for YoutubeYouTube

Copyright © 2026 Global X. All rights reserved.

Privacy PolicyAccessibility Statement

SEI Investments Distribution Co. (1 Freedom Valley Drive, Oaks, PA, 19456) is the distributor for the Global X Funds.

Check the background of SIDCO and Global X's Registered Representatives on FINRA's BrokerCheck.

Content
Thought LeadershipEmerging MarketsGreece

Greece Outlook 2024: Market Friendly Policies and Valuations Create Potentially Attractive Backdrop

x
M
Multiple authors
Feb 6, 2024·3 min read

With a backdrop of strong momentum, discounted valuations, attractive yields, and market friendly governance, we believe Greece continues to hold promise for a strong 2024. As it maintains a limited 0-1% exposure in the benchmark MSCI Emerging Markets Index, global funds have largely overlooked this market, suggesting untapped potential for new investors.

Key Positives

  • Valuations: Despite recent growth and Investment Grade sovereign risk, Greece's equity market (as measured by the MSCI Greece Index) remains undervalued, trading below book value.1

  • Profitability: Low multiples alone aren’t enough for an investment case, in our opinion. We are just as encouraged by the elevated levels of profitability amongst Greek companies. The market now carries a return-on-equity (ROE) profile above 14%, which is more than double the level of profitability the market produced in 2019.2

  • Growth: Importantly, Greece boasts superior near-term GDP (gross domestic product) growth potential, which could translate into opportunities for accretive reinvestment. Greek GDP is projected to grow 2.9% in 2024 versus 1.3% in the E.U.3,4

  • Yield: The MSCI Greece Index’s 7.3x price-to-earnings (P/E) multiple translates into a 13.6% earnings yield.5 From a dividend perspective, the market is rewarding investors with a dividend yield above 5%.6

  • Macroeconomic Outlook: We have seen strong macro indicators, fueled by increased investments, expanding exports, and a thriving tourism sector.

  • Debt Profile & Governance: Greece has an appealing sovereign debt profile with an average maturity of 17 years at fixed rates, accompanied by a market-friendly government and a stable political landscape.7

  • Financial Sector: The Greek banking sector has been rejuvenated following extensive cleanup and deleveraging, coupled with a robust non-banking space generating substantial cash flows to support continuous growth.

  • Politics: The market friendly New Democracy party recently gained a majority in parliament, allowing Prime Minister Mitsotakis to continue his pro-business agenda while also accelerating the pace of reforms. We recently saw the Prime Minister speak where he said that he was going “full throttle on reforms.”8

Potential Equity Market Catalysts

  • Continued distribution of Recovery & Resilience Facility (RRF) funds from the E.U.

  • Expected debt upgrades

  • Government asset sales

  • IPO market revival

  • Liquidity infusion from the Hellenic Financial Stability Fund

  • Prospects of inclusion in MSCI's developed market watch list

  • Reintroduction of banking dividends

  • Signs of growth recovery within the European Union

  • Continued progress on reforms

The Banking Sector Stands Out


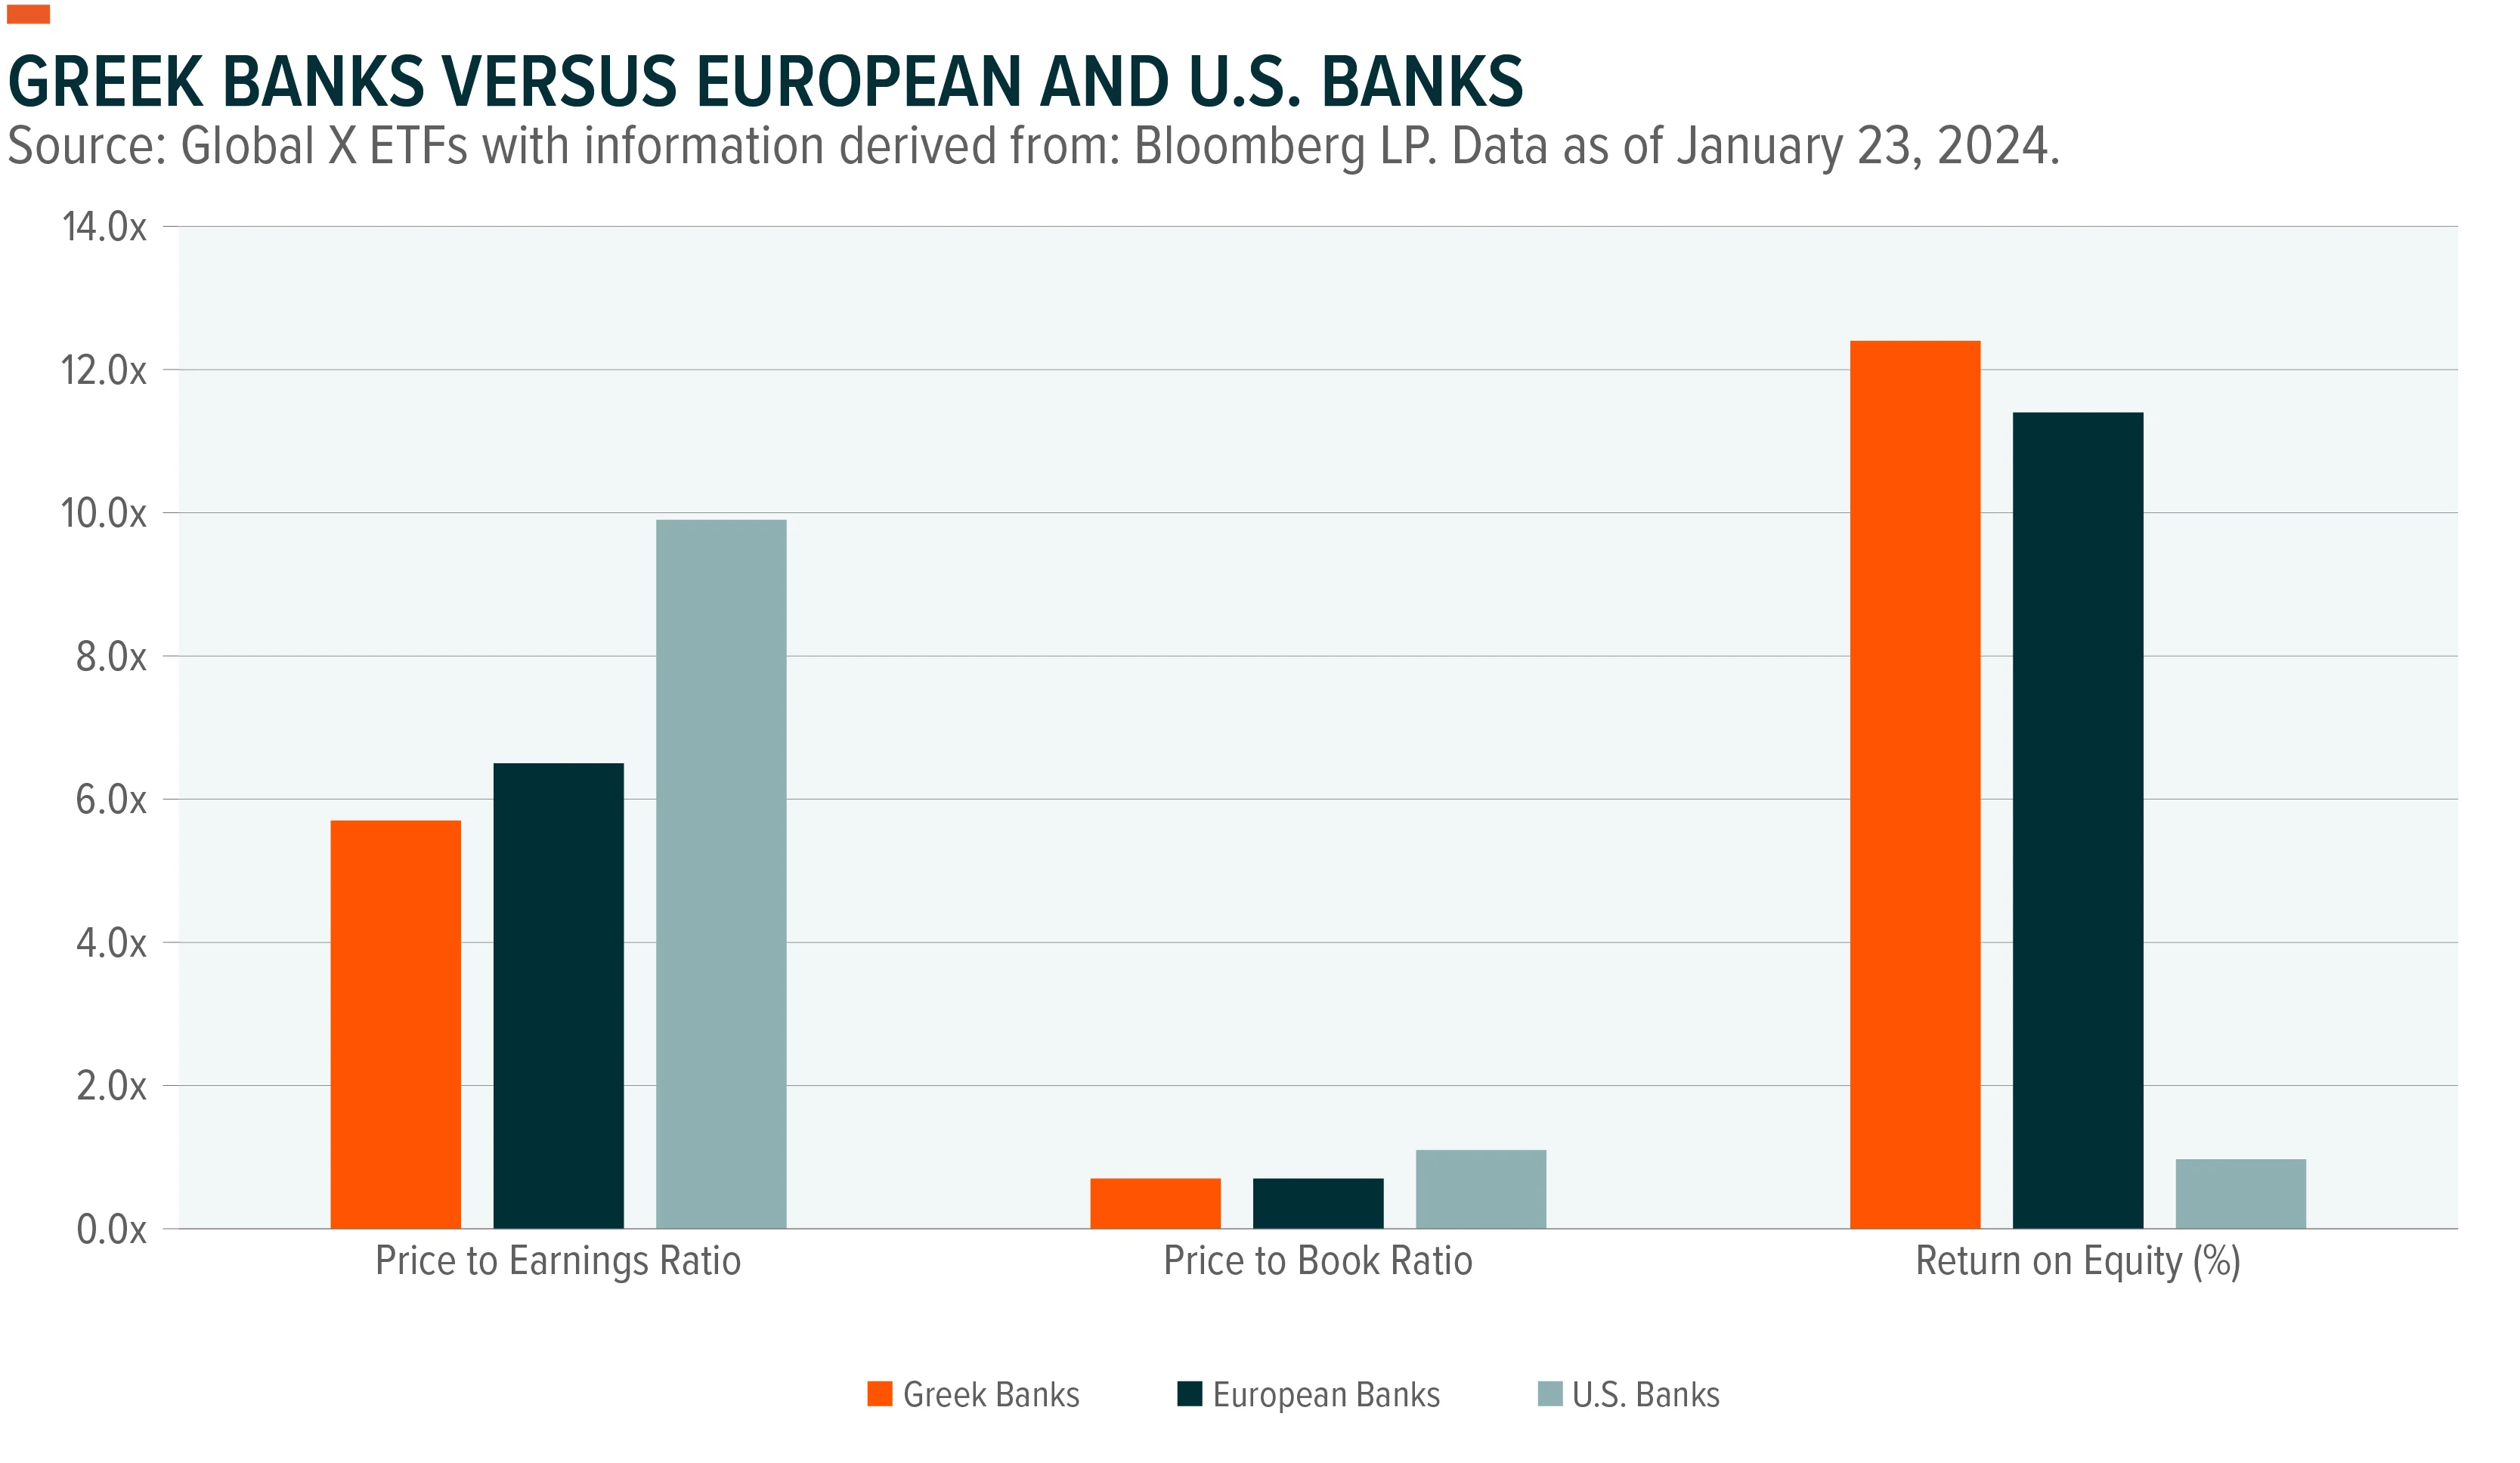
Banks represent 48.5% of the MSCI Greece Index.9 On average, Greek banks now trade at a discount to E.U. peers.10 However, we believe Greek banks offer significantly more upside when considering:
 

  • 240201-Greece-Outlook_01

Insights From Our Meeting with Finance Minister Hatzidakis

Conclusion


We believe Greek equities still have considerable room to run, even after the MSCI Greece Index returned 49% to investors in 2023.15 We remain positive on the investment case due to 1) the continuity of the pro-business and stable political environment, 2) valuations remaining attractive from a historical and relative perspective at 7x earnings, and 3) the many potential catalysts, such as the resumption of bank dividends and an eventual upgrade to developed market status by MSCI, that may still materialize. For these reasons, we believe Greece remains the best value opportunity within emerging markets.
Greek banks trade at 5.7x earnings and 0.66x book value with 12.4% ROEs.11

The strong GDP growth outlook for Greece versus the E.U.could translate into higher loan growth, as investments in Greece remain supported by E.U. recovery funds.

Net income will likely be supported by a continued structural reduction in provisions, as non-performing exposure (NPE) levels normalize towards E.U. average levels.

We anticipate higher profitability levels for Greek banks relative to E.U. peers.

Greek banks are more sensitive to rate cuts than E.U. peers.We also believe that higher loan growth and under penetrated fee and commission income will support net income.

We expect Greek banks to begin paying dividends again beginning in March of 2024.

Reform Agenda: Minister Hatzidakis reiterated a commitment to accelerating reforms while preserving a pro-business environment. The focus lies on making the Greek economy more dynamic and productive through a balance of fiscal prudence and a business-friendly approach.

Economic Outlook: Forecasts predict GDP growth of 2.9% for 2024, surpassing the Eurozone's projected 1.3%.12,13 Key metrics show improvements in debt-to-GDP ratios, reduced unemployment (~10%), and an upsurge in foreign direct investment (FDI) to 15% of GDP, albeit still below E.U. peers (~22%).14

Future Prospects: Despite past underinvestment, Greece now boasts a credible E.U. central bank, low post-election political risks, and an influx of E.U. funds into private enterprises, paving the way for a decade of potential growth and opportunities.

Related articles

1of3
Thought LeadershipArgentinaEmerging Markets

10 Things We Like About Argentina: Feedback From Argentina Week

M

Multiple authors

Mar 18, 20264 min read
Thought LeadershipEmerging MarketsInternational

Colombia: Value, Votes, and a Venezuelan Tailwind

Thought LeadershipIndiaEmerging Markets

India as a Long-Term Standalone Investment

Thought LeadershipArgentinaEmerging Markets

10 Things We Like About Argentina: Feedback From Argentina Week

Related funds
International
GREKMSCI Greece ETF
Explore All ETFs
Footnotes

1. Bloomberg LP. Data as of January 23, 2024.

2. Ibid.

3. Reuters. (2023, Nov 21). Greek Economy Seen Growing By 2.9% Next Year on Strong Investment.

4. Financial Times. (2023, Nov 15). European Commission Cuts Growth Forecasts After ‘Challenging Year.’

5. Bloomberg LP. Data as of January 23, 2024.

6. Ibid.

7. Ibid.

8. Kathimerini. (2024, Jan 26). PM Highlights Greek Economic Progress, Reform Commitment.

9. Bloomberg LP. Data as of January 23, 2024.

10. Ibid.

11. Ibid.

12. Reuters. (2023, Nov 21). Greek Economy Seen Growing By 2.9% Next Year on Strong Investment.

13. Financial Times. (2023, Nov 15). European Commission Cuts Growth Forecasts After ‘Challenging Year.’

14. Government figures provided by Finance Minister Hatzidakis during his meeting with Global X on December 11, 2023.

15. Bloomberg LP. Data as of January 23, 2024.

Argentina Week left us with a renewed sense of confidence that the country is entering a structural turning point after decades of volatility.

Argentina Week left us with a renewed sense of confidence that the country is entering a structural turning point after decades of volatility.

Colombia appears priced for pessimism, but upcoming elections and regional recovery potential could create a compelling opportunity for investors.

P

Paul Dmitriev

Feb 27, 20265 min read

We believe India’s compelling demographics, market friendly governance, and distinctive risk/return profile make it an attractive standalone investment.

M

Multiple authors

Sep 10, 20253 min read
M

Multiple authors

Mar 18, 20264 min read
Thought LeadershipEmerging MarketsInternational

Colombia: Value, Votes, and a Venezuelan Tailwind

Colombia appears priced for pessimism, but upcoming elections and regional recovery potential could create a compelling opportunity for investors.

P

Paul Dmitriev

Feb 27, 20265 min read
Thought LeadershipIndiaEmerging Markets

India as a Long-Term Standalone Investment

We believe India’s compelling demographics, market friendly governance, and distinctive risk/return profile make it an attractive standalone investment.

M

Multiple authors

Sep 10, 20253 min read