Thought LeadershipArgentinaEmerging Markets
10 Things We Like About Argentina: Feedback From Argentina Week
M
Multiple authors
Mar 18, 20264 min read
Get the latest news and updates from our team.
Paul Dmitriev
Paul Dmitriev
Multiple authors
SEI Investments Distribution Co. (1 Freedom Valley Drive, Oaks, PA, 19456) is the distributor for the Global X Funds.
Check the background of SIDCO and Global X's Registered Representatives on FINRA's BrokerCheck.
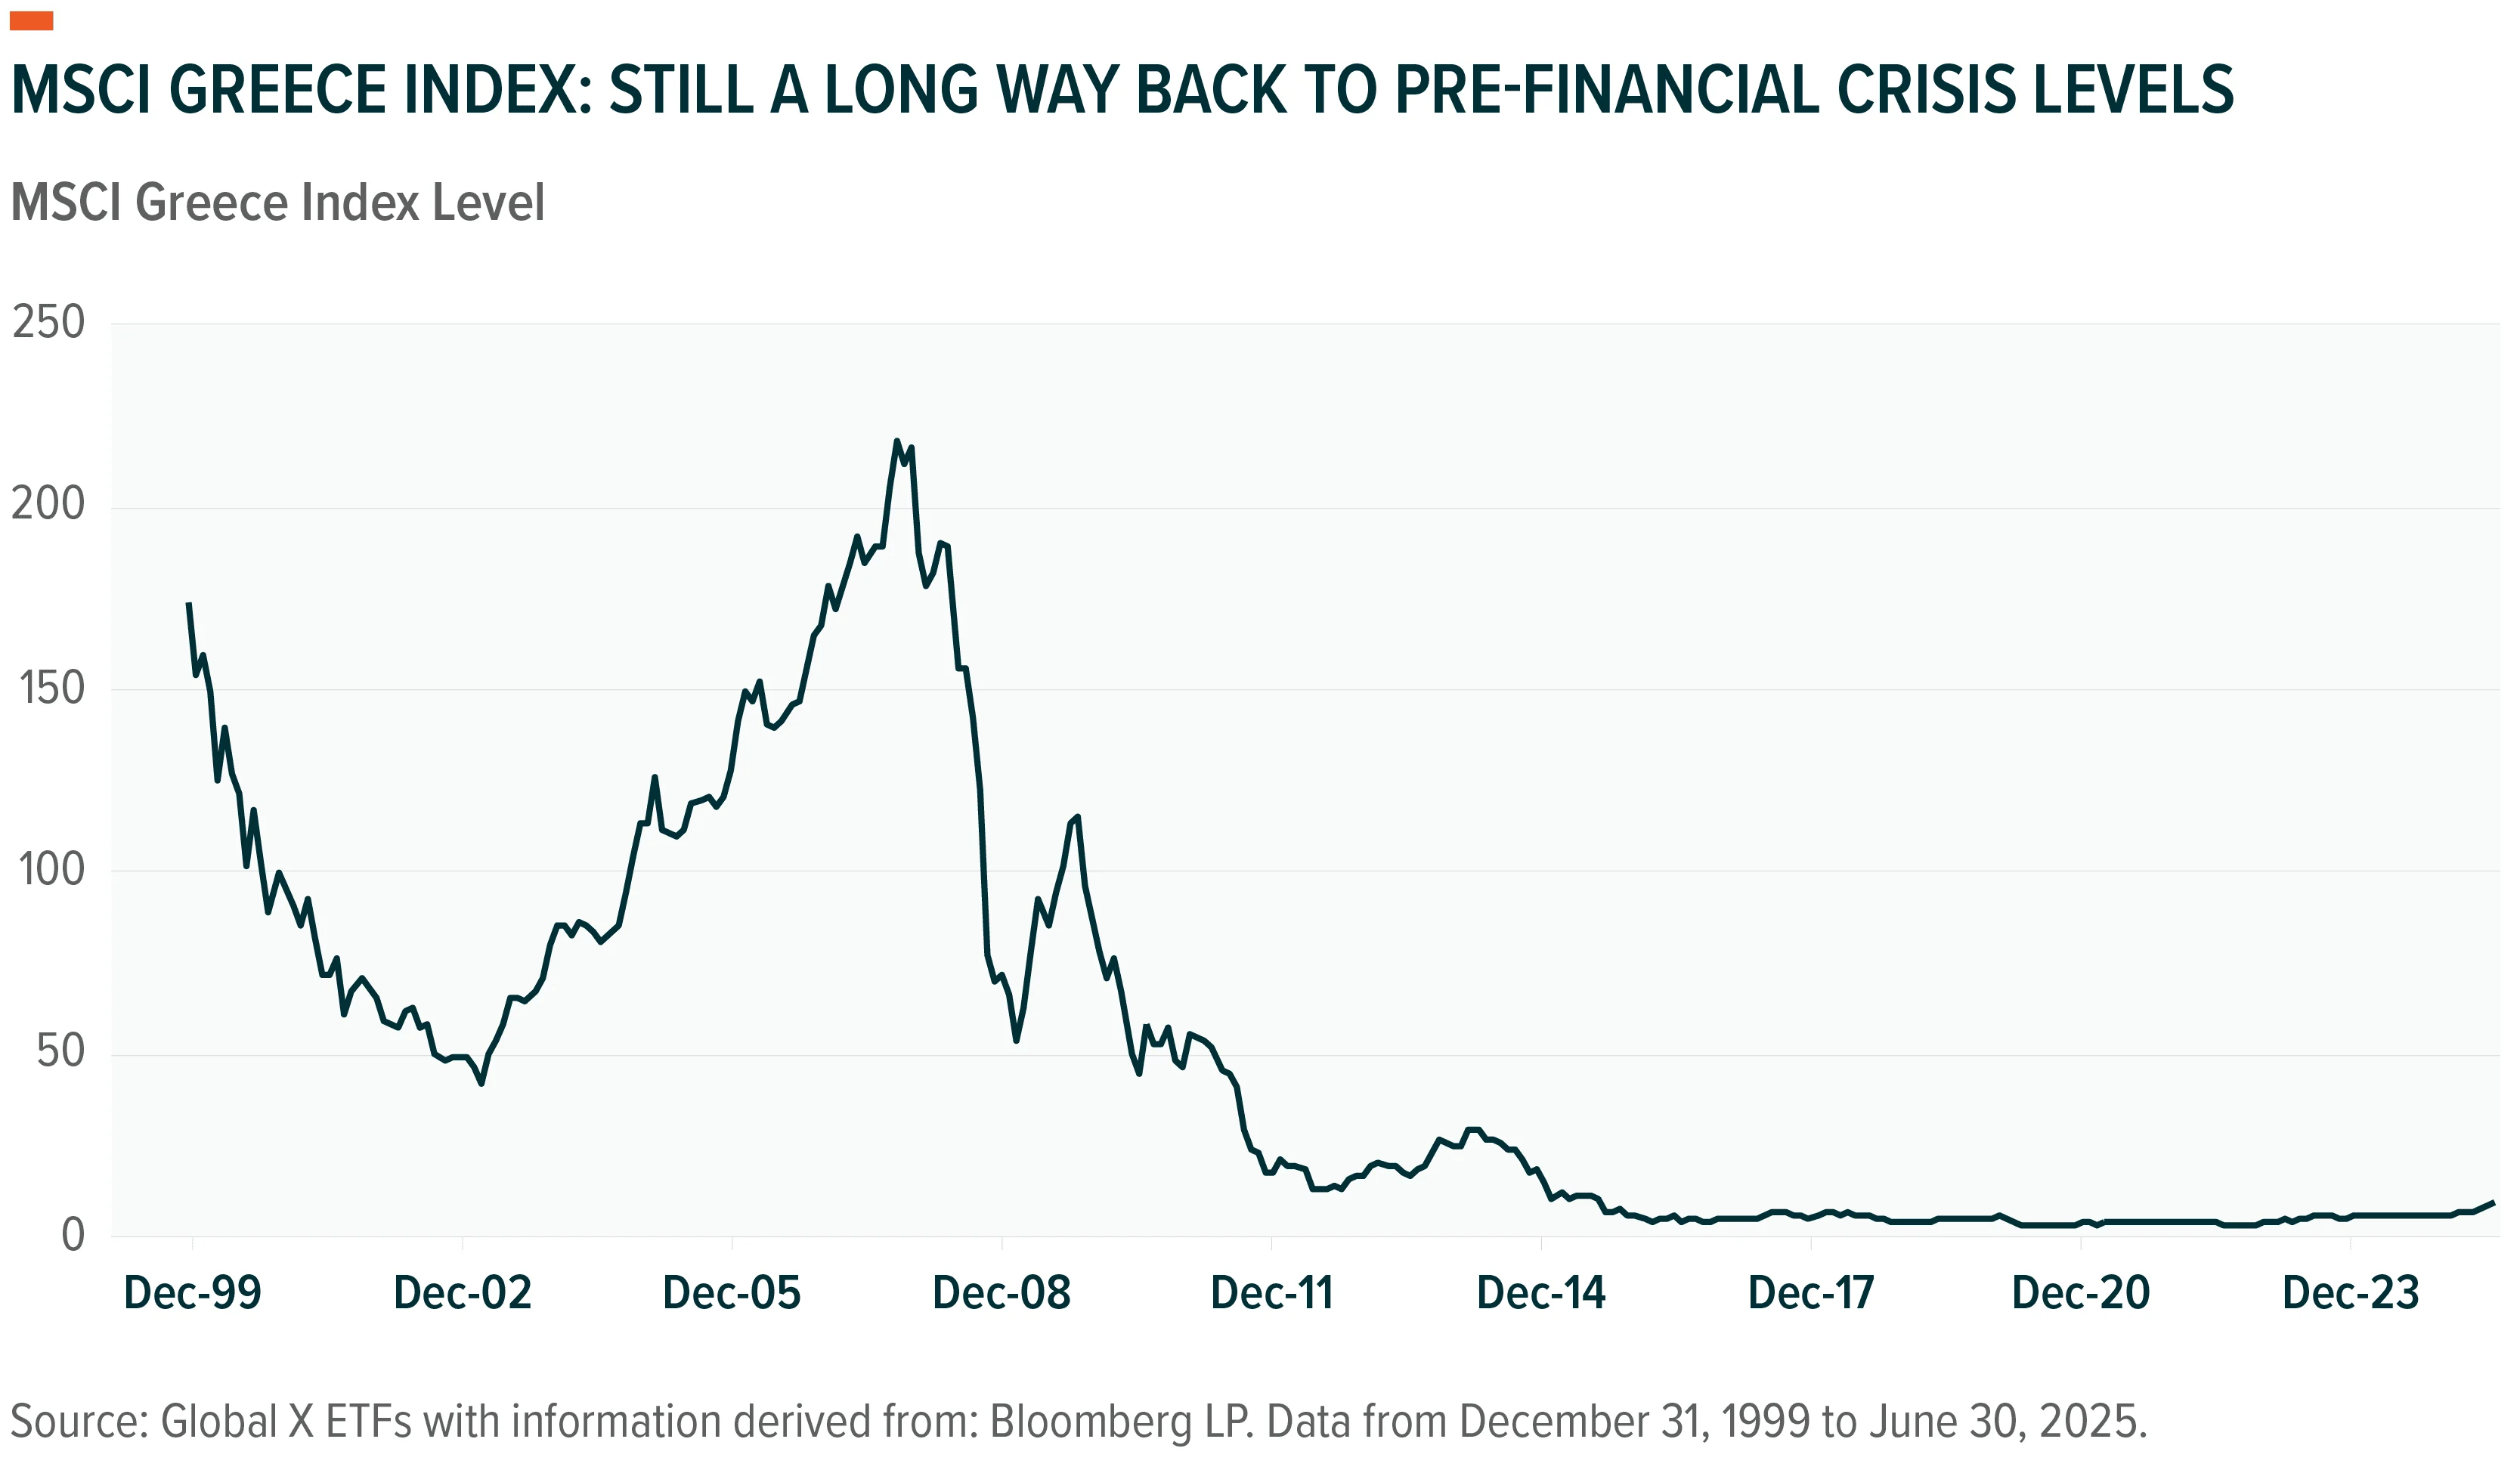
Greek equities have demonstrated robust momentum in 2025, with the MSCI Greece Index (Net) returning over 67.6% year to date through July 15th.1 Structural reforms, fiscal discipline, and a favorable macroeconomic environment all underpinned this performance. Despite recent gains, valuations remain attractive, and we see clear potential catalysts on the horizon. Greece still makes up less than 0.7% of the benchmark MSCI Emerging Markets Index, reinforcing our view that Greek equities appear overlooked and under-owned.2
Valuations: Greek equities trade at a forward price-to-earnings (P/E) ratio of approximately 8.6x and a price-to-book (P/B) ratio of around 1.2x, compared to the S&P 500's P/E of over 21.0x and P/B nearing 4.4x.3 This valuation discount persists despite improved macroeconomic indicators and earnings growth.
Governance: Moody’s upgraded Greece to investment-grade status in March 2025, marking the end of a 15-year period of sub-investment-grade ratings. The upgrade reflects enhanced fiscal performance, institutional stability, and commitment to reforms.4 Furthermore, Greece continues to benefit from its membership in the EU and Eurozone, with the euro providing greater stability versus the pre-2002 drachma.
Growth: The European Commission projects Greece's GDP will grow 2.3% in 2025, outpacing the estimated Eurozone average of 1.3%.5 Growth drivers include increased private investment, EU Recovery and Resilience Facility (RRF) fund deployment, and a strong tourism sector. Furthermore, a gradual recovery towards the EU Investment-to-GDP average of 23%, back to pre-financial crisis levels, is coinciding with a significant improvement in the banking sector ROE toward 15%.6
Positioning: The Athens Stock Exchange has experienced a resurgence, with market capitalization increasing by €20 billion over the eight months through May 2025, finally catching up to pre-2008 levels.7
Geopolitics: Greece maintains a stable political environment with a pro-business government, reducing geopolitical risk. The country's strategic location and EU membership provide access to broader markets while maintaining regional neutrality. Additionally, Greece’s main export comes from services (in the form of tourism), meaning that it boasts a low risk profile in terms of tariffs.
Catalysts: Potential reclassification of Greek equities to Developed Market status by FTSE Russell and MSCI could attract significant passive inflows. We believe Euronext's discussions to acquire the Athens Stock Exchange may enhance market integration and investor access.
Greek equities may offer a compelling investment opportunity, combining Emerging Market growth prospects with Developed Market stability. We think the confluence of attractive valuations, structural reforms, and favorable macroeconomic trends positions Greece as a strategic addition to diversified portfolios.
1. Bloomberg. Data as of July 15, 2025.
2. Ibid.
3. Ibid.
4. Moody’s. (2025, Mar 14). Moody's Ratings Upgrades Greece's Ratings to Baa3 From Ba1, Changes Outlook to Stable From Positive.
5. European Commission. (2025, May 19). Economic Forecast for Greece.
6. European Commission. (2024, Apr).
7. Athens24. (2025, Jun 7). Athens Stock Exchange Soars With 35% Rally and EUR20 Billion Growth in 8 Months.
8. Finance Feeds. (2025, Jul 2). Euronext in Talks to Acquire Athens Stock Exchange in EUR399M Deal.
Argentina Week left us with a renewed sense of confidence that the country is entering a structural turning point after decades of volatility.
Argentina Week left us with a renewed sense of confidence that the country is entering a structural turning point after decades of volatility.
Colombia appears priced for pessimism, but upcoming elections and regional recovery potential could create a compelling opportunity for investors.
Colombia appears priced for pessimism, but upcoming elections and regional recovery potential could create a compelling opportunity for investors.
We left a recent trip to Brazil optimistic that depressed equity valuations could present an attractive buying opportunity.
We left a recent trip to Brazil optimistic that depressed equity valuations could present an attractive buying opportunity.